
What if I can't afford my payday loan payment?
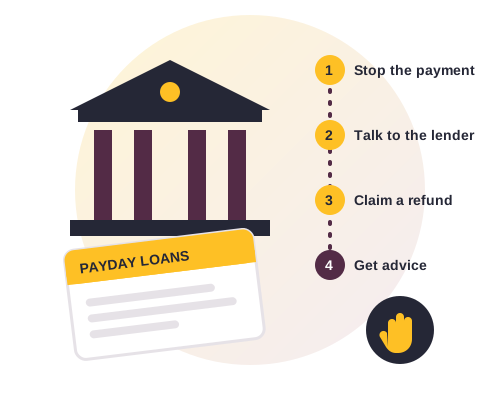
Act before the payment date. Payday loans are non-priority debts, but because the lender can take money straight from your account, they can leave you short for rent, energy and food.
- Protect your essentials. If paying would leave you without money for priority bills, stop the payment before it's taken.
- Contact the lender. Explain your situation and ask for more time or an affordable repayment plan. Lenders must treat you fairly and take your circumstances into account.
- Don't borrow again to pay it. Another payday loan, or a bigger one, usually makes things worse.
- Keep to any new plan you agree, to avoid more charges.
- Get advice, especially if you have more than one payday loan or other debts. Debt Breathing Space stops interest, charges and collection for 60 days.
I have more than one payday loan
You don't have to deal with each lender on your own. A debt adviser can look at all your loans, bills and income together and work out what you can afford. Taking out another loan to repay existing ones is how many people end up trapped.
What happens if I miss a payday loan payment?
- Charges and interest are added, within the price cap. The default fee can't be more than £15.
- The lender will contact you and may try to take the payment again from your card.
- Missed payments and defaults go on your credit file. A default stays for six years.
- The debt may be passed to a debt collection agency. Collectors aren't bailiffs and have no extra powers.
- The lender can take you to court for a County Court Judgment. Don't ignore court papers: you can offer affordable payments.
You can't go to prison for not repaying a payday loan, and lenders can't send bailiffs unless they get a CCJ and you then don't pay it.
What is the payday loan price cap?
Since 2 January 2015, FCA rules limit what high-cost short-term lenders can charge:
| Rule | What it means for you |
|---|---|
| Daily cap | Interest and fees can't be more than 0.8% a day of the amount borrowed, including after a rollover |
| 30-day example | No more than £24 in interest and fees for every £100 borrowed for 30 days, if you repay on time |
| Default fee | No more than £15, and interest on unpaid amounts can't be higher than the original rate |
| Total cost cap | You'll never pay back more in interest and fees than you borrowed. Borrow £200, repay no more than £400 in total |
If a lender has charged more than this, complain.
How do I stop a payday lender taking money from my account?
Most payday lenders take repayments using a continuous payment authority (CPA), sometimes called a recurring payment. You give them your card details, and they take the money on the due date. Unlike a Direct Debit, the amount and date can change.
The rules on CPAs
- If a payment fails, the lender can only try twice in total.
- It shouldn't take part payments through a CPA.
- You have the right to cancel a CPA directly with your bank or card provider. It must stop the payments straight away, and can't insist you agree it with the lender first.
How to cancel
- Tell your bank or card provider to stop the CPA, by phone, online or in writing, at least a day before the payment is due.
- Tell the lender in writing that you've withdrawn permission for it to take payments.
- Check your account. If money is taken after you've cancelled, it's an unauthorised payment and your bank should refund it, including any charges it caused.
For a Direct Debit or standing order, cancel it with your bank in the same way. Stopping payments doesn't cancel the debt, so contact the lender to agree how you'll repay.
Should I roll over my payday loan?
A rollover (or extension) moves your repayment to a later date, usually with a new agreement. It can feel like breathing room, but more interest and fees are added, so you end up owing more.
- Lenders can't roll a loan over more than twice.
- Each time, they must give you an information sheet about free debt advice.
- Only consider it if the problem is genuinely short term and you're sure you can clear the loan next time.
Can I get a refund if the loan was unaffordable?
Lenders must check you can afford to repay before they lend. If they didn't, you can complain. Signs a loan was unaffordable include:
- you took a new payday loan to repay an earlier one
- you borrowed repeatedly, or the loans kept getting bigger
- you missed rent, bills or food to make the repayments
If your complaint is upheld, you could get back interest and charges you paid, have balances reduced and have the loans removed from your credit file. The Financial Ombudsman Service usually adds 8% simple interest to refunds.
- Gather details of your loans. You can ask the lender for your loan history.
- Complain to the lender in writing, explaining why the loans weren't affordable.
- Go to the Financial Ombudsman Service if you're not happy with the final response, or you've heard nothing after eight weeks. You usually have six months from the final response.
In a Debt Relief Order? A refund received during a DRO could affect it, because your assets must stay under £2,000. Get advice before you claim.
What can I do instead of a payday loan?
- Check your benefits. Many people miss out on help they're entitled to. Use an online benefits calculator.
- Universal Credit budgeting advance, or a short-term advance if you're waiting for your first payment.
- Your council's local welfare assistance scheme, for emergency help with essentials.
- A credit union loan, which costs far less than a payday loan.
- Your energy supplier's hardship fund if you're behind on gas or electricity.
- A food bank or furniture scheme if you need essentials.
If you do borrow, check the lender is authorised on the FCA register. Never pay a fee upfront to get a loan: it's a common scam.
Debt solutions that can help with payday loans
| Debt solution | Can it include this debt? |
|---|---|
| Debt Breathing Space | Yes |
| Debt Management Plan | Yes |
| IVA | Yes |
| Debt Relief Order | Yes |
| Bankruptcy | Yes |
A payday loan can't simply be written off because you're struggling, but a DRO, IVA or bankruptcy can write it off. Compare all your debt options, or read why searching for terrible credit loans is a warning sign.
Payday loans piling up?
Tell us about your debts and a licensed insolvency practitioner will call you back to talk through your options. It's free, with no obligation.
Questions about payday loan debt
What should I do if I can't pay my payday loan?
Contact the lender before the due date, ask for more time or an affordable plan, and stop the payment if it would leave you short for essentials. Don't borrow again to pay it, and get free debt advice.
Can a payday lender keep taking money from my account?
Only twice if a payment fails, and not as part payments. You can cancel the continuous payment authority with your bank, which must stop it straight away.
Can you go to jail for not paying a payday loan?
No. Payday loans are consumer credit, and not repaying them isn't a criminal offence.
Can a payday loan company take me to court?
Yes. A lender can apply for a County Court Judgment. If you then don't pay as ordered, it could use bailiffs or other enforcement.
How much can a payday loan cost?
Interest and fees are capped at 0.8% a day, the default fee at £15, and you'll never repay more than double what you borrowed.
How long does a payday loan stay on my credit file?
Your payment history is recorded on your file. A default stays for six years from the date of default.
Can I get money back from a payday lender?
If the lender didn't properly check you could afford the loan, you can complain. You could get interest and charges refunded, plus 8% interest if the Financial Ombudsman Service upholds it.
Can a payday loan be written off?
Not just because you're struggling. But a Debt Relief Order, IVA or bankruptcy can write off payday loan debt.
