
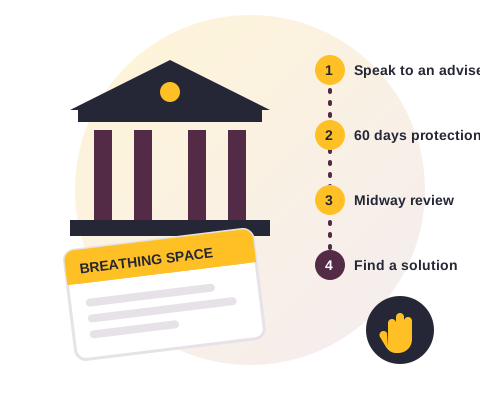
What is Breathing Space?
Breathing Space, officially the Debt Respite Scheme, is a government scheme in England and Wales. It gives you legal protection from your creditors for up to 60 days while you get debt advice and work out a long-term solution.
During Breathing Space, most creditors can't take enforcement action, can't contact you about the debts included, and can't add interest or charges. It isn't a debt solution itself and it doesn't write off any debt. It gives you time to choose the right option.
The two types of Breathing Space
| Standard Breathing Space | Mental health crisis Breathing Space | |
|---|---|---|
| Who it's for | Anyone in problem debt who meets the conditions | People receiving mental health crisis treatment |
| How long | Up to 60 days | As long as the crisis treatment lasts, plus 30 days |
| How often | Once every 12 months | No limit |
| How to apply | Through a debt adviser | Through a debt adviser, with evidence from an approved mental health professional. Someone else can apply for you. |
Does Breathing Space stop bailiffs?
Yes, for the debts included. Once your Breathing Space starts, for qualifying debts such as council tax arrears, parking penalties or a CCJ:
- a creditor can't start bailiff action
- a bailiff can't take control of your goods, so visits to list or take goods must stop
- if a bailiff already removed goods before your Breathing Space started, they can still sell them, but they can't charge you for storing them during or after it
- Show the bailiff your Breathing Space confirmation if they contact you, and tell your debt adviser. Your creditors are told automatically, but it helps to let the bailiff firm know too.
- Court fines aren't covered, so bailiffs collecting magistrates' court fines can carry on. Parking penalties (PCNs) are covered, because they aren't criminal fines.
- Council tax: if you're still paying by monthly instalments, keep paying them. If the council has sent a reminder or the whole year's bill has become due, that debt is covered and you don't have to keep paying it during Breathing Space.
Breathing Space is one of the 10 ways to stop bailiffs. You can also ask bailiffs for more time.
What else Breathing Space protects you from
| Breathing Space stops | Breathing Space doesn't stop |
|---|---|
| New court action, including County Court claims | An attachment of earnings order already in place |
| Enforcement of a court judgment you already have | Deductions from Universal Credit |
| Bankruptcy petitions and statutory demands | Action on debts that aren't covered, like court fines |
| Most eviction and repossession claims for arrears | Your ongoing rent, mortgage and bill payments |
| Energy disconnection, and fitting a prepayment meter for the debt | Interest or action on debts taken out after it starts |
| Creditors and debt collectors asking you to pay | Creditors sending statements and legally required letters |
Benefit deductions: if you get older benefits such as income-based JSA, ESA, Income Support or Housing Benefit, deductions for a covered debt should stop. If you get Universal Credit, they carry on. If a deduction was paying something important, such as rent arrears, arrange another way to pay.
Old debts: if a debt is close to becoming "statute barred" (too old to take to court), the creditor's time limit is extended by 8 weeks after Breathing Space ends. Get advice before including a very old debt.
Who can get Breathing Space?
- You must live in England or Wales.
- You must be unable to pay some or all of your debts as they fall due. It's more likely to help if you're already behind. If you're up to date and can afford your payments, it probably isn't right for you.
- You must not have a Debt Relief Order, an IVA or an interim order, or be an undischarged bankrupt.
- You must not already be in Breathing Space, or have had a standard Breathing Space in the last 12 months.
Your debt adviser must also agree that you need time to get advice and are likely to go on to a debt solution.
Self-employed? Business debts aren't covered if your business is VAT registered, or you're in a partnership and the debt relates only to the business. Business Debtline can advise.
Live in Scotland? Breathing Space isn't available, but you may be able to apply for a debt moratorium. See our Protected Trust Deed page for more about Scottish options.
Applying is free, although some debt advisers may charge. Free advisers are available through MoneyHelper, National Debtline, StepChange, Citizens Advice and others.
Which debts are covered?
| Usually covered | Not covered |
|---|---|
| Credit cards, store cards and overdrafts | Magistrates' court fines |
| Personal loans and payday loans | Student loans |
| Council tax arrears | Child maintenance and family court orders |
| Rent and mortgage arrears | Social Fund crisis and budgeting loans |
| Energy and water arrears | Universal Credit advance payments |
| Most tax and benefit debts | Debts from fraud |
| Parking penalties (PCNs) | Damages for death or personal injury |
| Joint debts and guarantor loans | Council tax that isn't due yet |
All your qualifying debts go in. You can't pick and choose. If you miss one out by mistake, your adviser can add it later, but it's only protected until your Breathing Space ends.
- Mortgages, secured loans and hire purchase: the arrears can be included, but you must keep up your normal monthly payments.
- Joint debts: the other person is also protected from enforcement on that debt, but missed payments can affect their credit file too. They aren't added to the register and may need their own advice.
- Guarantor loans: the guarantor isn't protected and can still be chased.
How does Breathing Space work?
- Speak to a debt adviser. You can't apply on your own. The adviser checks that you qualify and that Breathing Space is right for you.
- The adviser applies. They send your details and your list of creditors to the Insolvency Service.
- Breathing Space starts. Your details are added to a private register, usually by the end of the next working day, and your protection starts the day after. Your creditors are told.
- Midway review. Between days 25 and 35, your adviser checks that you're still taking part in debt advice and keeping up your ongoing payments.
- You choose a solution. Such as a DMP, IVA, DRO or bankruptcy.
- Breathing Space ends. After 60 days, or earlier if it's cancelled or you start a debt solution.
What you must do during Breathing Space
- Keep paying your ongoing bills, such as rent or mortgage, current council tax and energy. Breathing Space isn't a payment holiday.
- Keep paying your debts if you can. GOV.UK says you still need to make your repayments, although interest and charges are frozen.
- Stay in touch with your adviser and take part in the midway review. If you don't, your Breathing Space can be cancelled.
- Don't borrow more than £500 during Breathing Space.
- Keep paying any insurance, and your own tax and National Insurance if you're self-employed.
- Tell your adviser about any change in your circumstances, such as a new job.
- Cancel direct debits to creditors in your Breathing Space, as some may still take payments. If you live on an overdraft or credit card, you may lose access to it, so consider a basic bank account with a bank you don't owe money to.
If you genuinely can't afford your ongoing bills, your Breathing Space usually won't be cancelled for that alone. Speak to your adviser.
Can it be cancelled? Yes. Your adviser can end it after the midway review. A creditor can ask your adviser to review it if they think you don't qualify, their debt shouldn't be included, or you can afford to pay. If they're unhappy with the outcome they can go to court, and you may have to pay their costs if the court agrees with them. Once ended, it can't be restarted.
Mental health crisis Breathing Space
This gives the same protections as standard Breathing Space, but it lasts for as long as your crisis treatment, plus 30 days. You qualify if you're:
- detained for assessment or treatment under the Mental Health Act 1983
- taken to a place of safety under the Mental Health Act
- getting crisis, emergency or acute care from a specialist mental health service, such as a crisis or home treatment team
An approved mental health professional (AMHP) must confirm your treatment. You don't need to be getting debt advice, someone else can speak to the adviser for you, there's no limit on how often you can have it, and you can have one even if you've had a standard Breathing Space in the last 12 months. Referrals go to We Are Group in England or Citizens Advice in Wales, and MoneyHelper has details.
Will Breathing Space affect my credit file?
Breathing Space is held on a private register. Only the Insolvency Service, your adviser and the creditors included can see it, and each creditor only sees their own debt. If having your address on it could put you at risk of violence, ask your adviser to leave it off.
Breathing Space itself doesn't go on your credit file and isn't a form of insolvency. But creditors still report missed payments as normal, and a lender may keep its own record, which could affect borrowing from them in future.
How Bailiff Helpline works: Breathing Space can only be applied for through a debt adviser. If you ask us to, we pass your details to a licensed insolvency practitioner from our panel, who may pay us a fee. They can talk you through your options. Free debt advisers who can apply for Breathing Space are also available through MoneyHelper.
Need some breathing space from bailiffs?
Tell us about your debts and a licensed insolvency practitioner will call you back to talk through your options. It's free, with no obligation.
Questions about Breathing Space
What is Breathing Space?
Breathing Space, or the Debt Respite Scheme, is a government scheme in England and Wales that gives you up to 60 days' legal protection from creditors while you get debt advice. Creditors can't take enforcement action, contact you about the debts, or add interest and charges.
Does Breathing Space stop bailiffs?
Yes, for the debts included, such as council tax arrears, parking penalties and CCJ debts. Bailiffs must stop enforcement for those debts. Magistrates' court fines aren't covered.
How long does Breathing Space last?
Standard Breathing Space lasts up to 60 days. Mental health crisis Breathing Space lasts as long as the crisis treatment, plus 30 days.
How do I apply for Breathing Space?
You apply through a debt adviser. You can't apply on your own. Free advisers are available through MoneyHelper, National Debtline, StepChange and Citizens Advice.
How much does Breathing Space cost?
Applying is free. Some debt advisers may charge, but free advisers are widely available.
Do I still have to pay my debts during Breathing Space?
You should keep paying if you can, and you must keep up your ongoing bills such as rent, current council tax and energy. Interest and charges on the debts included are frozen.
Can council tax arrears go into Breathing Space?
Yes. If the council has sent a reminder or the whole year's bill is due, it's covered. If you're still paying by monthly instalments, keep paying them.
Can bailiffs sell goods they've already taken?
Yes. If a bailiff removed goods before your Breathing Space started, they can still sell them, but they can't charge you storage fees during or after Breathing Space.
Does Breathing Space stop an attachment of earnings?
It stops a creditor starting a new one, but an attachment of earnings order that's already in place carries on.
Does Breathing Space stop eviction?
In most cases, your landlord or mortgage lender can't start court action over arrears during Breathing Space. You must keep paying your normal rent or mortgage.
Can I get Breathing Space in Scotland?
No. Breathing Space covers England and Wales only. In Scotland, you may be able to apply for a debt moratorium.
How often can I get Breathing Space?
Standard Breathing Space can be used once every 12 months. There's no limit on mental health crisis Breathing Space.
Will Breathing Space affect my credit rating?
Breathing Space isn't public and doesn't go on your credit file itself. But creditors can still record missed payments.
What happens when Breathing Space ends?
Your creditors can contact you again and add interest and charges. That's why you should use the time to set up a long-term solution, such as a DMP, IVA, DRO or bankruptcy.
Can my Breathing Space be cancelled?
Yes. Your adviser can cancel it after the midway review, a creditor can ask for a review or go to court, and it can end if you don't keep up your ongoing payments. It can't be restarted once it ends.
